Who at Your Home Care Agency Actually Has Health Coverage?
Twenty-three percent of part-time workers in private industry have access to employer medical benefits. Forty-six percent of home care workers are part-time. Hold those two numbers against your own roster and the honest answer at most agencies is the owner, maybe an office manager who brought coverage in from a hospital job, and nobody who actually goes into a client's house. You solved your own coverage years ago. That is why the question stopped getting asked.
When did you last read your own careers page?
Pull it up and read the benefits line. Flexible schedule, paid training, competitive pay. Now read the same line on three competitors in your county, including whichever national franchise brand is nearby, and you will find a list so close to identical that it could have been written once and copied around. Health coverage is missing from almost all of it.
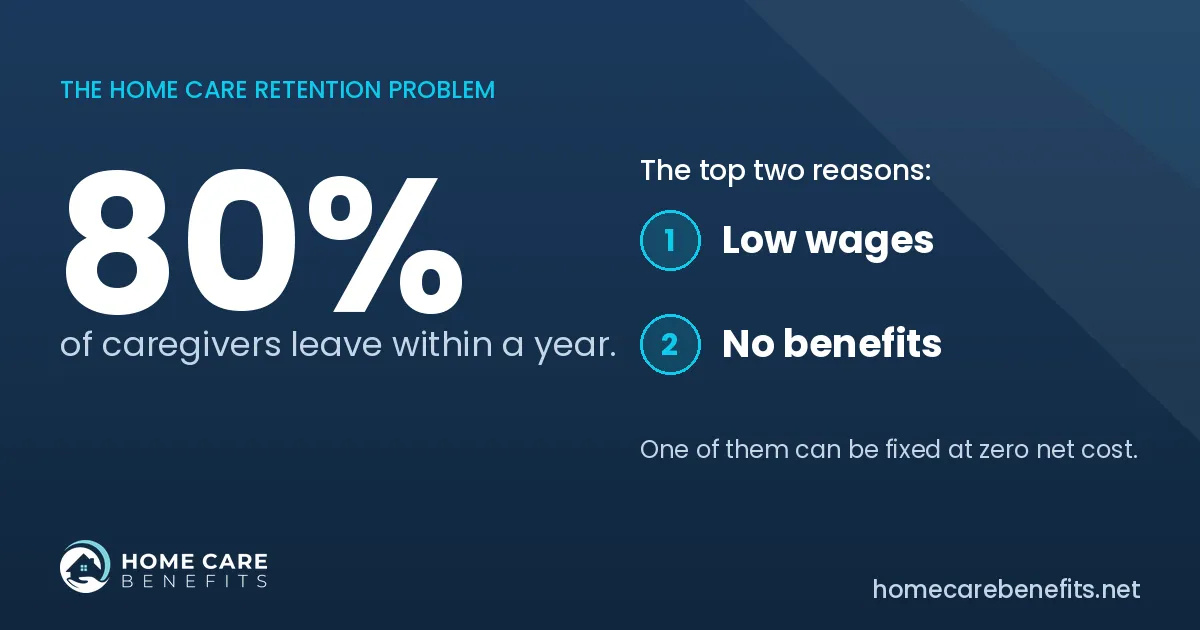
Here is the part that is nobody's fault. Most owners sorted out their own coverage long before the roster reached forty, through a spouse's employer or a policy bought in their thirties. A problem you personally solved stops appearing in your week. Eleven percent of home care workers carry no health insurance and 48 percent sit on public coverage, most of it Medicaid, per PHI's 2025 key facts report.
So who at the agency actually has coverage?
Three groups, and they barely overlap. You and any family on the payroll. An office or scheduling hire who brought a plan in from a spouse. Then the caregivers, where 46 percent work fewer than 35 hours a week and the thirty-hour group health threshold rules most of them out before anybody bothers to run a quote. Nobody in that group was asked.
The federal numbers say the same thing without mentioning home care once. Access to employer medical benefits runs at 39 percent among private industry workers in the lowest quarter of wages, against 94 percent in the top quarter, per the Bureau of Labor Statistics for March 2026.
| Who | What they usually have | Why |
|---|---|---|
| You, the owner | Coverage, bought somewhere else | Solved personally, years before the agency grew |
| Office and scheduling | Sometimes, often through a spouse | Full-time hours, higher wage band |
| Caregivers | Medicaid, or nothing | Hourly, part-time, under the carrier's threshold |
Price explains the rest. Family coverage through an employer averaged $28,303 a year in 2026, per KFF's annual employer survey. Whether you can be in a plan yourself is a separate question with an awkward answer.
My caregivers are part-time. Does any of this reach them?
Not quite. The thirty-hour rule is a group health carrier's eligibility line, and it has nothing to do with the tax code. A Section 125 election is open to W-2 employees regardless of hours worked, which is the single reason this structure fits a roster of three-day-a-week caregivers when a group plan cannot. Hours are not the gate here.
Wages are. What each caregiver nets depends on pay rate, filing status and what is already coming out of the check, so a caregiver at ten hours a week can net nothing. The part-time options sit side by side here.
The plan carries a CPA opinion from CBIZ and a legal assurance letter from HitesmanLaw. Our compliance page lists both, and the legitimacy question is worth reading before you talk to any vendor.
I ran these numbers already and we cannot afford it
You ran the wrong two options. A raise and a group plan both need money that is not currently in the business, and on a 7 to 10 percent net margin there is no version of that arithmetic that works, which is exactly what you found the evening you closed the spreadsheet. Here is the raise you priced, and what it runs across forty.
A Section 125 wellness plan asks for none of that. It redirects employer payroll tax the agency already sends to the Treasury, which puts the net employer cost near zero. Where those payroll taxes go is broken out line by line here.
Where this stops
This is not insurance. A caregiver who needs surgery, a hospital stay or a specialist consult is as exposed afterwards as before. It also will not reach your whole roster, because what each caregiver earns decides that, and the ones working the fewest hours are the likeliest to net nothing.
The roster you most want to help is where this works least well. An agency already carrying a group plan keeps it and adds this underneath.
What would this look like at your agency?
Two inputs answer it: how many caregivers, and what they earn. That is the whole ask, and it stays small on purpose. The estimator takes those two numbers and shows what you pay in employer payroll tax now, what turnover at the industry median costs you, and what could be redirected into caregiver benefits instead. Thirty seconds, no signup.
Across Home Care Benefits' own proposals the employer figure has landed between $300 and $900 per participating employee per year. That is a range and not a quote. Which of your caregivers qualify, and what shows up on their checks, only your own numbers answer. Have your CPA read the plan documents. Nothing to send us, nothing to upload.
Home Care Benefits is not a law firm, an accounting firm, or an insurance company, and provides marketing and enrollment support rather than legal, tax, accounting or health advice. The Unify Wellness Plan is administered by UnifyWell and ACA Solutions. The plan is not health insurance. Savings figures in any proposal are estimates based on the information provided and are not guaranteed. Federal and state tax laws change. Consult your own CPA or attorney before enrolling.